In one line. Some UAE banks are offering one-year fixed mortgages from 3.75%, and buyers are moving to lock in before rate cuts slow (Khaleej Times, 2026).
Best for. Mortgage buyers deciding between fixed and variable, and cash buyers weighing whether cheap debt changes the math.
What you will learn.
- Where UAE mortgage rates actually sit now
- Why they track the US Federal Reserve
- The real trade-off between fixed and variable
- How to decide without trying to time the market
Bottom line. Rates have eased, and a fixed period buys you certainty. That certainty is worth paying for if it protects a deal that already works. It is not a reason to buy a deal that only works at the lowest possible rate.
Where Rates Sit Now
The headline numbers. Major UAE banks have advertised one-year fixed rates from 3.75%, two-year products around 3.78%, and three-year fixes near 3.95% (Khaleej Times, 2026). Average residential mortgage rates through 2026 have sat in a band of roughly 3.89% to 4.99%, so the sharpest teaser rates undercut the typical offer.
The backdrop. The Central Bank of the UAE base rate sits at 3.65% after a run of cuts, and three-month EIBOR has been fixed near 3.85% in 2026. Those are the reference points your variable rate is built on, so when they move, your payment moves with them.
| Rate | Level |
|---|---|
| CBUAE base rate | 3.65% |
| 3-month EIBOR | ~3.85% |
| 1-year fixed (from) | 3.75% |
| 3-year fixed (approx.) | 3.95% |
Why Dubai Follows the Fed
The peg does the work. Because the dirham tracks the dollar, the Central Bank of the UAE broadly mirrors the Fed's rate decisions to keep the peg stable. The easing UAE borrowers have seen since 2025 reflects US cuts, not a separate local policy.
Slow, not fast. With the Fed moving cautiously, UAE borrowers should expect gradual cuts rather than a sharp drop. That is the honest reason behind the "lock in now" pitch: nobody is promising rates will fall quickly from here, so the certainty of a fix looks more attractive.
What it means for you. You cannot outguess the Fed, and neither can your bank. Treat the direction as uncertain and build your decision around what you can control: the deal, the deposit, and the payment you can comfortably carry.
Fixed vs Variable
Fixed. You know your payment for the fixed term, which makes budgeting and yield math clean. The cost is flexibility: many fixed products carry early-settlement fees, and if rates fall further you do not benefit until the fix ends.
Variable. You ride EIBOR plus a bank margin. If cuts continue, your payment can fall. If they stall or reverse, it rises. Variable suits borrowers with headroom in their budget and a plan to settle early.
Read the full cost, not the teaser. The 3.75% headline usually applies to year one, then reverts to a variable rate of EIBOR plus a margin. Ask for the reversion rate and the early-settlement terms before you sign, because that is what you actually pay for most of the loan.
How to Decide
- Stress-test at a higher rate. If the purchase only works at 3.75%, it is too tight. Check that it still works two points higher.
- Match the fix to your horizon. Selling in two years? A three-year fix with early-settlement fees may cost more than it saves.
- Compare the reversion rate. The rate after the fixed period matters more than the headline for a long hold.
- Keep costs in cash. Since 2025, DLD fees and related charges must be paid upfront in cash, so budget those separately from the loan.
The Bottom Line
The honest caveat. Advertised rates change weekly and the lowest ones carry conditions on salary, deposit and property type. Confirm the full offer with your bank and a mortgage adviser, and treat any single rate you see quoted as a starting point, not a promise.
"A fixed rate is insurance, not a bargain. Buy it to protect a deal that works, never to rescue one that doesn't."
Weighing fixed against variable?
We stress-test your purchase across rate scenarios and compare the true all-in cost of each mortgage structure.
Book a 30-minute advisory call →Frequently Asked Questions
What is the lowest mortgage rate in Dubai right now?
Some banks advertise one-year fixed rates from 3.75%, though average rates in 2026 have sat between roughly 3.89% and 4.99% depending on the product and borrower (Khaleej Times, 2026).
Why do UAE rates follow the US?
The dirham is pegged to the US dollar, so the Central Bank of the UAE broadly mirrors US Federal Reserve decisions to keep the peg stable.
Should I fix or go variable?
Fixed buys payment certainty for a set term; variable keeps you exposed to rate moves. Match the choice to your hold period and check early-settlement fees.
Will rates keep falling in 2026?
Expect slow, gradual moves rather than sharp cuts, because the US Fed is easing cautiously and UAE rates track it. Nobody can promise the direction, so plan for uncertainty.
What is the catch with a 3.75% rate?
It usually applies to year one, then reverts to EIBOR plus a bank margin. Ask for the reversion rate and settlement terms, since that is what you pay for most of the loan.
Sources cited in this article
- Khaleej Times : Dubai homebuyers rush to lock in fixed-rate mortgages as rates drop to 3.75%
- Gulf News : UAE central bank cuts key interest rate, tracking the US Fed
Get AYAN, YAZDAN’s free property app A live off-plan map of 1,700+ UAE projects, a full UAE mortgage calculator, and OS-level spam-call protection. Free on iOS and Android. Get the AYAN app → | 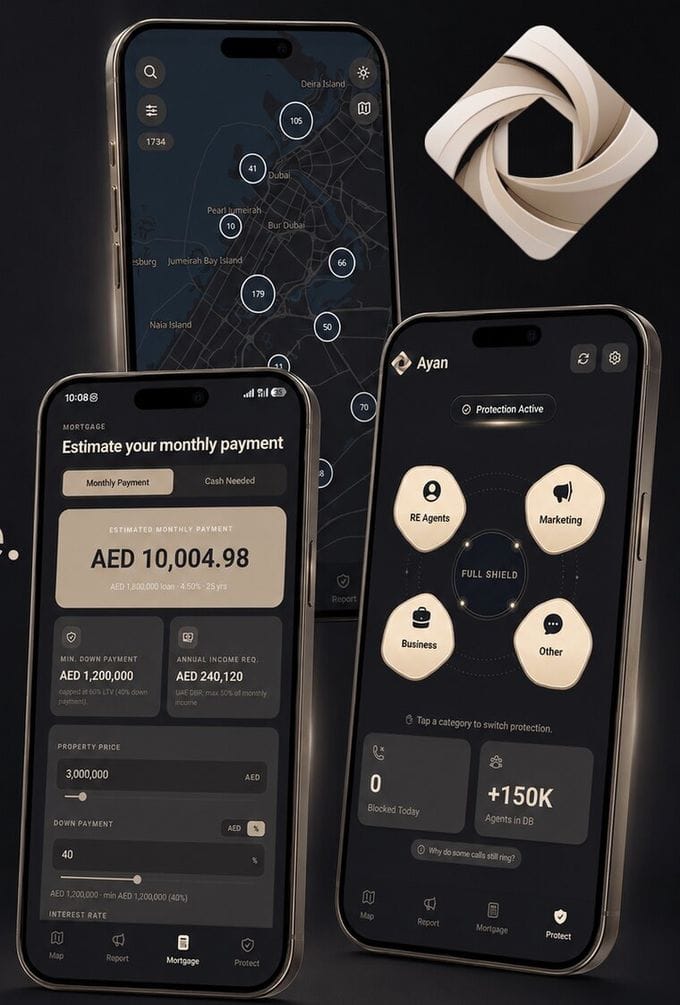 |
- YAZDAN Off-Plan Map: browse every current off-plan project across the UAE on one live map
- AYAN app: YAZDAN’s companion app for investors and buyers
YAZDAN Properties models fixed versus variable across rate scenarios and checks the all-in cost, so your financing protects the deal rather than stretching it.
Book a 30-minute advisory call →
Or email info@yazdan.ae directly.
Editorial analysis for information only, not financial advice. Rates change frequently; confirm current terms with your bank and a licensed mortgage adviser before any decision.