In one line. Developers say flexible payment plans are now central to closing sales, with one firm's 10-year plan making up 80% of its bookings and others offering no down payment and 1.5% monthly instalments (The National, 9 September 2026).
Best for. Off-plan buyers comparing payment plans, and investors checking whether an easy plan hides a hard cost.
What you will learn.
- Why developers are leaning on payment plans this year
- What a post-handover plan really costs you
- The questions that separate a good plan from a trap
- How to compare a plan against a mortgage
Bottom line. A generous plan lowers the cash you need upfront, not the price you pay. Read the schedule and the premium, then compare it against a mortgage before you decide it is a bargain.
Why Plans Are Front and Centre
The shift. At the International Property Show in September, developers described flexible payment structures as central to closing deals. One cited a plan with no down payment and a 1.5% monthly instalment. Another said its 10-year payment plan now accounts for 80% of total bookings (The National, 9 September 2026).
Why now. Buyers have turned cautious and price-conscious this year. Rather than cut the headline price, many developers stretch the payment timeline, which lowers the monthly outlay and widens the pool of people who can say yes. It is a way to keep sales moving without formally discounting.
The trade-off is real. A longer, softer plan is genuinely useful for cash flow. It also tends to come attached to a price that already builds in the developer's cost of carrying you. The convenience is real, and so is the premium.
What the Plans Actually Cost
Post-handover plans. These let you keep paying after you get the keys, often over five to ten years. That eases cash flow, but the unit's price is usually set higher than a comparable ready home to reflect the developer financing you for years at no interest on paper.
The hidden comparison. A no-down-payment, 1.5%-monthly plan sounds cheaper than a mortgage until you compare total cost. With a mortgage you pay interest but often buy at a keener price, and you own the asset outright sooner. Run both to the same end date before you judge which is cheaper.
Escrow still applies. Off-plan payments in Dubai flow into a project escrow account released against construction milestones, which protects your money if the project stalls. A payment plan does not change that protection, but you should still confirm the project is registered and the escrow is active before you pay anything.
Questions Before You Sign
- What is the cash price? Ask what the same unit costs paid in full. The gap is the true cost of the plan.
- What happens if I miss a payment? Check the penalty and cancellation terms before you rely on the schedule.
- Can I sell before I finish paying? Confirm the resale and assignment rules, and any developer fee to transfer.
- Is the project registered with DLD? Verify the escrow account and construction status before the first instalment.
To see which projects offer which plans and how they cluster by area, the YAZDAN Off-Plan Map gives you live off-plan inventory across Dubai and the UAE on one view, so you can compare terms before you commit.
The Bottom Line
Use it well. If a plan lets you hold cash back for renovation, furnishing, or a second deposit, that flexibility has genuine value. Just price it against the cash alternative so you know what the flexibility costs.
The honest caveat. Plan terms vary by developer and project, and the most generous ones can carry the steepest built-in premium. Get the cash price and the full schedule in writing, and compare against a mortgage before you sign.
"A payment plan changes when you pay, not what you pay. Get the cash price first, then decide whether the flexibility is worth the premium."
Comparing a payment plan against a mortgage?
We price both to the same end date and surface the built-in premium, so you know what the flexibility actually costs.
Book a 30-minute advisory call →Frequently Asked Questions
Why are Dubai developers offering such easy payment plans?
With buyers more selective in 2026, developers compete on terms to keep sales moving. One firm reported its 10-year plan now makes up 80% of bookings (The National, 9 September 2026).
Is a post-handover plan cheaper than a mortgage?
Not necessarily. Plans spread the cost but the unit price often builds in a premium for the developer financing you. Compare total cost to the same end date.
Is my money safe on an off-plan payment plan?
Off-plan payments flow into a DLD-regulated escrow account released against construction milestones. Confirm the project is registered and the escrow is active before paying.
Can I sell before I finish the plan?
Often yes, but confirm the developer's resale and assignment rules and any transfer fee before you rely on selling mid-plan.
What is the single most important question to ask?
What the same unit costs paid in cash. The gap between that and the plan price is the true cost of the flexibility.
Sources cited in this article
- The National : Dubai property demand shifts to mid-market, payment plans central to deals
- Property Finder : DLD fees and off-plan escrow explained
Get AYAN, YAZDAN’s free property app A live off-plan map of 1,700+ UAE projects, a full UAE mortgage calculator, and OS-level spam-call protection. Free on iOS and Android. Get the AYAN app → | 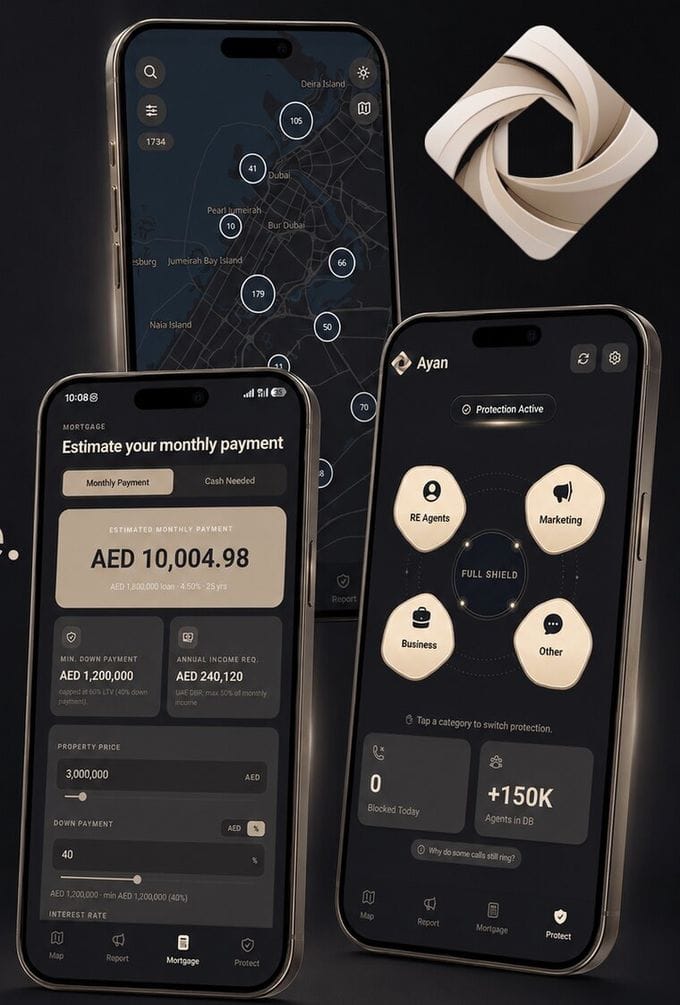 |
- YAZDAN Off-Plan Map: browse every current off-plan project across the UAE on one live map
- AYAN app: YAZDAN’s companion app for investors and buyers
YAZDAN Properties reads the schedule, surfaces the built-in premium and compares it against a mortgage, so a generous plan is a real advantage rather than a hidden cost.
Book a 30-minute advisory call →
Or email info@yazdan.ae directly.
Editorial analysis for information only, not financial advice. Plan terms vary; confirm the cash price, schedule and escrow status via DLD and the developer before any decision.